
Quick Summary
Standard business policies routinely exclude flood damage, making dedicated commercial flood insurance coverage through the NFIP or private insurers vital for safeguarding property assets. As specialists at Wade's Restoration emphasize, expediting claim payouts requires combining immediate physical mitigation with carrier-compliant documentation, including itemized inventories and photo evidence. Commercial property managers can request a professional visual inspection and carrier-ready documentation support to navigate policy limits and secure fast claim settlements.
Commercial Flood Insurance Coverage: How Documentation Can Support a Claim
When overland floodwater or severe storm runoff inundates a commercial building, every passing hour compounds the physical damage. For commercial property owners, retail operators, and warehouse managers, understanding commercial flood insurance coverage is critical to managing out-of-pocket loss. According to government data compiled by the U.S. Government Accountability Office (GAO), the proportion of National Flood Insurance Program (NFIP) commercial policyholders buying at maximum statutory building limits rose from 21% to 36% between 2002 and 2012. Businesses increasingly recognize their physical exposure, but securing payment after a loss requires precise, timely documentation.[1]
As professionals at Wade’s Restoration emphasize, a successful settlement relies on pairing timely physical mitigation with clear evidence, such as photographic records, inventories, and repair estimates to substantiate direct physical loss. See also Basement Flood Cleanup | Call Now-10% Off | Same-Day Service | Free Estimate.
What Does Commercial Flood Insurance Coverage Actually Include?
Commercial flood insurance coverage pays for direct physical loss caused by flooding. Standard commercial property insurance policies generally exclude flood damage. Building owners and commercial tenants usually must secure separate flood coverage through the federal government via the NFIP or through private flood insurers.
Standard Commercial Property Exclusions vs. Flood Coverage
Because standard commercial property insurance policies generally exclude flood damage, protecting a business from external flooding typically requires a separate NFIP policy or private flood coverage.[5]
Building Property vs. Business Personal Property Limits
Under the standard NFIP commercial framework, coverage is divided into two separate, capped categories:
- Building Property (up to $500,000 under NFIP): Protects eligible building structures up to the NFIP statutory limit.
- Business Personal Property (up to $500,000 under NFIP): Protects commercial contents and inventory up to the NFIP statutory limit.
NFIP vs. Private Commercial Flood Insurance: Key Differences
Federal coverage through the NFIP offers standardized coverage with statutory limits of up to $500,000 for building property and $500,000 for contents. Private commercial flood insurance policies may offer higher limits and broader terms.[4]
| Feature | NFIP Direct | Private Flood Policies | Standard Property Policy |
|---|---|---|---|
| Building Limit | Up to $500,000 (NFIP Limit) | Higher limits may be available | Generally Excluded |
| Contents Limit | Up to $500,000 (NFIP Limit) | Higher limits may be available | Generally Excluded |
| Business Interruption | Not Available | May be available | Generally Excluded (Floods) |
NFIP Statutory Coverage Limits
The standard $500,000 NFIP building cap and $500,000 contents limit provide a baseline, but larger commercial properties may exceed these statutory amounts. According to historical data from the Insurance Information Institute, the average commercial flood claim from 2010 through 2014 was nearly $89,000, representing a historical average rather than a current benchmark.[2]
Private Commercial Flood Coverage and Business Interruption
Standard NFIP policies do not include business-interruption coverage. Private commercial flood insurance may offer higher coverage limits and broader terms, including possible business-interruption protection to help cover operating losses during a post-flood closure.
Documenting Commercial Flood Claims
Need commercial flood insurance coverage?
We’re available now - call for a fast, free estimate.
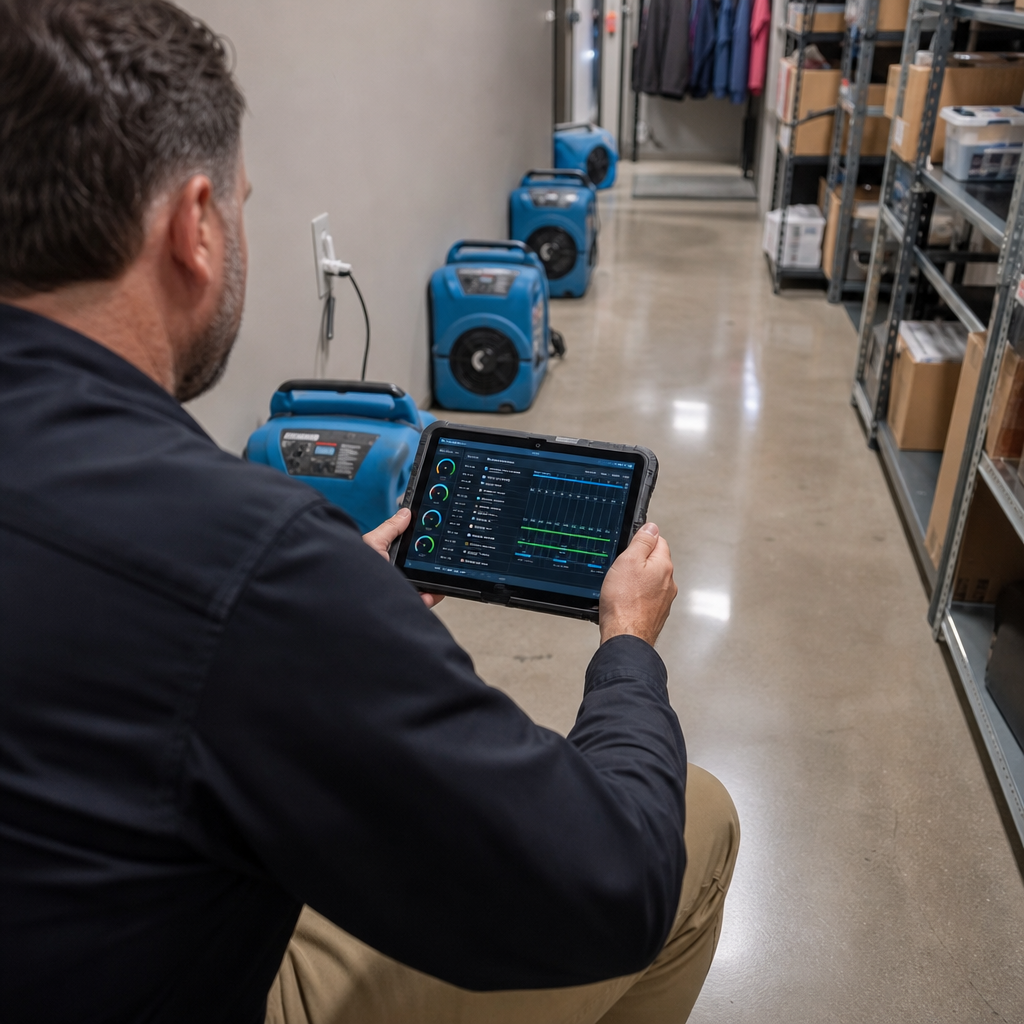
Commercial flood policies require appropriate documentation to substantiate physical damage and loss.
Mitigation and Property Documentation
According to technical guidance from Wade’s Restoration, commercial policyholders should act promptly to document property conditions and mitigate damage. Detailed records, photos, and inventories help demonstrate the scope of direct physical loss to an insurer.
What Does Commercial Flood Insurance Coverage Cover for Restoration?
Coverage for restoration and emergency mitigation services depends on specific policy terms, limits, deductibles, valuation rules, and exclusions.
Documenting Losses and Managing Business Impact
At least 25% of businesses that close after a disaster such as a flood reportedly never reopen, according to a reported historical statistic. Securing appropriate insurance payouts requires maintaining itemized inventories, photographic evidence, and thorough documentation of damaged property.[3]
Frequently Asked Questions About Commercial Flood Insurance Claims
Does a standard commercial property policy cover flood damage?
Flood damage is generally excluded from standard commercial property policies and usually requires separate coverage through the NFIP or a private flood insurer.
How does business interruption apply to commercial flood claims?
Business-interruption coverage is not available under standard NFIP commercial policies, but private flood coverage may offer broader terms that include possible business-interruption protection.
How are commercial flood restoration claims evaluated?
As noted by specialists at Wade’s Restoration, reimbursement for flood cleanup and restoration depends on the specific policy terms, coverage limits, applicable deductibles, valuation rules, and policy exclusions.
Need commercial flood insurance coverage?
We’re available now - call for a fast, free estimate.
Sources
- Flood Insurance: Implications of Changing Coverage Limits and Expanding Coverage – gao.gov (2012)
- FLOOD INSURANCE – gao.gov (2012)
- Six Reasons Businesses Need Flood Insurance – agents.floodsmart.gov (2021)
- NFIP Summary of Coverage Commercial Property – agents.floodsmart.gov
- An Agent's Guide to Selling Flood Insurance – agents.floodsmart.gov
Related reading: What to Do When Pipe Bursts – Call Now-10% Off – Same-Day Service – Free Estimate
Related reading: Roof Leak Mold – 10% Off & Free Estimate – On-Site in 60 Minutes
Related reading: Pipe Burst Water Damage – Call Now-10% Off – On-Site in 60 Minutes – Free Estimate
Frequently Asked Questions
What documentation is required to ensure a commercial flood claim is paid quickly?
Adjusters require date-stamped photographic evidence, detailed moisture mapping, an itemized inventory of ruined contents, and professional dry-out logs. Partnering with Wade's Restoration ensures property managers secure carrier-ready documentation and inspection reports that substantiate direct physical loss from day one.
What options exist if commercial flood damages exceed the $500,000 NFIP limit?
When physical damage exceeds the standard $500,000 NFIP building cap, business owners must tap into private excess flood insurance or specialized commercial riders. Wade's Restoration assists commercial policyholders by categorizing structural damage versus business personal property to maximize payouts across both primary and secondary policies.
Does commercial flood insurance cover emergency water extraction and drying services?
Commercial flood policies generally cover necessary emergency mitigation, such as water extraction and structural drying, to prevent secondary damage like structural rot. Wade's Restoration delivers immediate mitigation alongside carrier-compliant reporting to ensure all emergency cleanup costs align with policy terms and deductibles.
About the author
 |
David Thorne David Thorne is a certified restoration professional with over 12 years of experience in the property damage industry. Holding a degree in Construction Management from the New York Institute of Technology, he specializes in structural drying and mold remediation. David’s extensive background in managing both residential and commercial losses ensures practical, actionable advice for property owners navigating unexpected disasters. |
Water damage, flood, or mold emergency?
We’re available now - call for a fast, free estimate.
Call Now - Free Estimate